Bulk vs Individual Insurance Purchasing for Last-Mile Contractor Networks
Bulk purchasing gives delivery networks negotiated rates and unified coverage control.
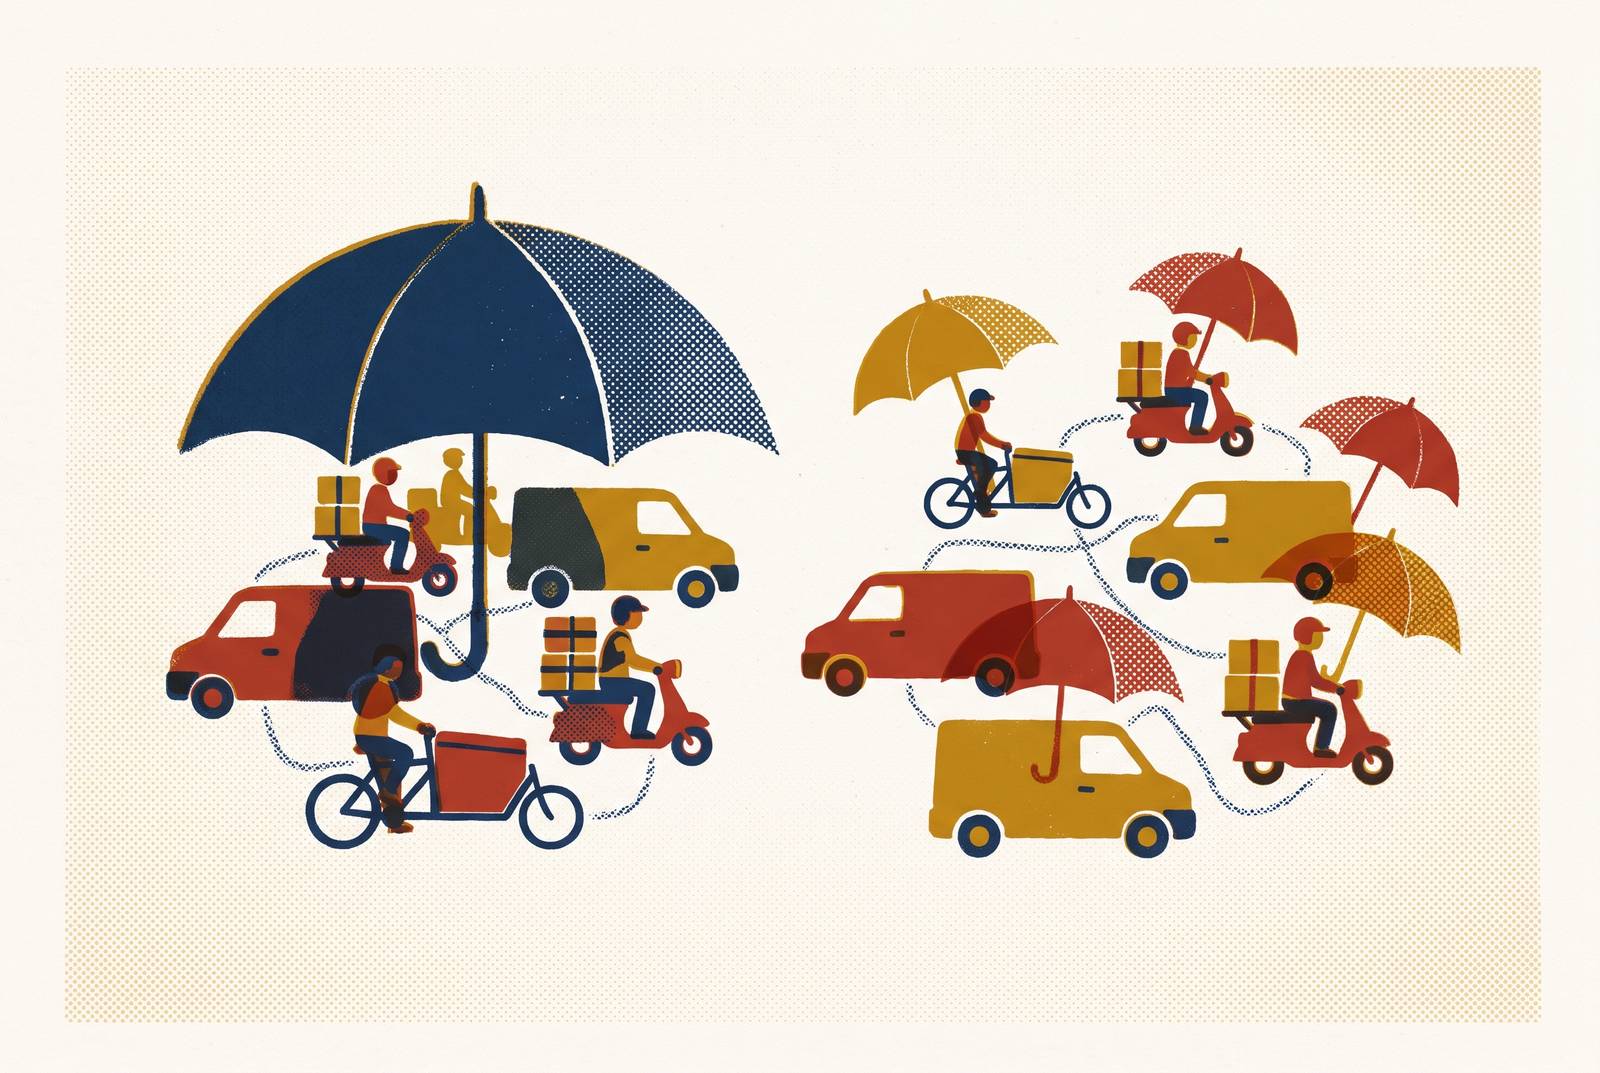
Bulk insurance purchasing gives last-mile delivery operators a structural advantage over individual contractor purchasing by combining negotiated group rates with centralized coverage control. For large independent contractor fleets, bulk occupational accident insurance can lower the cost per contractor and make injury protection easier to manage, but it must be part of a coverage stack whose policies work together. The strongest case for consolidation is not cheaper insurance alone, but fewer gaps between the risks an operator creates and the protection it controls.
Why last-mile contractor networks face a structurally different insurance problem than other gig categories
A last-mile delivery can expose a vehicle, its cargo, a contractor, and a third party to different kinds of loss at the same time. Commercial auto addresses vehicle liability, cargo insurance protects goods in transit, and general liability addresses third-party injury exposures. Occupational accident insurance, often shortened to occ/acc, protects the contractor against work-related injuries. These policies do different jobs. Having one does not establish that the others are in place.
The mismatch begins when a personal vehicle becomes a delivery vehicle without a corresponding change in coverage. Personal auto business-use exclusions can leave a driver uninsured for delivery work, with the gap beginning when the delivery app is turned on, before a delivery is accepted. The precise boundary depends on the policy. Operationally, however, the problem is straightforward because a vehicle can enter commercial service before the contractor has collected any goods or earned anything from the trip.
Hired and non-owned auto, or HNOA, addresses the operator’s liability exposure from vehicles it does not own but that operate on its behalf. It is an easily overlooked layer because the vehicle belongs to someone else. If a contractor causes an accident under dispatch and the personal insurer denies coverage, the dispatching operation can become a target of the claim. Contractor classification does not make that contingent liability disappear.
How individual contractor purchasing fails at every layer of the coverage stack
Individual purchasing assigns responsibility for a coordinated coverage stack to people buying separate products for separate reasons. A contractor might obtain injury protection while the operator’s HNOA exposure remains unaddressed. Another might buy commercial auto coverage and later let it lapse. Neither failure needs to be visible at onboarding. A complete file on the first day cannot establish coverage throughout the contract.
Across hundreds of contractors, this becomes a distributed monitoring problem. Each renewal, missed payment, and cancellation creates another point at which protection can change without a change in dispatch. The operator may learn of a gap only when a claim arrives. By then, verification has become an investigation. Individual contractors also enter the insurance market as single buyers, without the negotiating power of the network whose deliveries they perform.
Uber’s Optional Injury Protection illustrates the distinction between access to insurance and uniform enrollment. Uber describes the product as “completely optional,” with workers enrolling through the Driver app and authorizing per-mile premium deductions from earnings. That arrangement makes a product available but leaves the purchase decision with each worker. An operator-held arrangement instead places policy maintenance and coverage administration at the network level.
Fragmented purchasing therefore presents two separate weaknesses. Contractors cannot negotiate rates based on the whole network, and the operator cannot reliably maintain the full coverage stack by relying on their separate decisions. Injury protection alone cannot repair a missing auto-liability layer. Nor can a favorable individual premium compensate for a lapse the operator discovers after an accident.
What bulk purchasing actually is and how it works for a contractor network
With bulk purchasing, the operator holds one policy or a set of policies that work together, taking the place of many separate buying decisions. The operator negotiates coverage for the network and takes responsibility for maintaining the arrangement. This does not merge distinct exposures into one interchangeable product. Occ/acc, commercial auto, cargo, and HNOA still have separate functions. What changes is who controls their administration.
Risk pooling supplies the economic mechanism. Costs are spread across the contractor network rather than negotiated separately by each participant, allowing the claims of a smaller number of workers to be balanced across a broader group. That creates a basis for more predictable costs and lower per-contractor rates than fragmented purchasing can obtain. Aggregate buying power reinforces the effect.
Centralization also concentrates responsibility for keeping coverage active. Instead of tracking hundreds of independent payment and renewal decisions, the operator maintains the policy arrangement it controls. That responsibility moves to a place where it can be managed as an operating function.
Pay-as-you-go structures add another way to align premiums with exposure by tying charges to active dispatch periods. Under those arrangements, the operator pays for working time rather than a flat period that includes time when no delivery work occurs. Retail and third-party logistics, or 3PL, partners also commonly require a minimum combined single limit for liability coverage. With operator-held coverage, the business has one way to show that its whole network meets that contractual standard.
How can delivery companies reduce insurance costs for large independent contractor fleets?
Consolidating purchasing strengthens an operator’s position in a hardening insurance market. Commercial auto liability, physical damage, and umbrella liability premiums have trended sharply upward, making separate contractor purchases harder to sustain. Pooling gives the operator a way to negotiate against aggregate exposure in place of unrelated individual prices while remaining subject to market-wide increases.
The useful comparison is premiums for equivalent coverage. Group purchasing derives its advantage from pooling and negotiating scale while retaining every coverage layer. Any reduction in the per-contractor cost applies across the covered network. For a large fleet of drivers, the route to group rates on accident coverage is therefore an operator-negotiated occ/acc arrangement. The buying unit has to match the scale of the operation.
Contractor turnover adds another source of friction. When contractors buy on their own, each new arrival must shop for insurance, and each person who leaves has a separate purchasing arrangement left behind. Bulk coverage allows new entrants to be administered within the operator’s existing policy. Enrollment still needs management.
The strongest objection is that the operator assumes a premium expense previously paid by drivers. That is a real budget change, but it is not the creation of an entirely new exposure. Uninsured contractor accidents could already bring claims against the operation. Bulk purchasing turns some of that risk, which the operator has little control over, into a cost it can plan for with clear coverage. The cheaper-looking model may simply keep its most consequential costs off the budget until an accident reveals them.
How California's Proposition 22 made occ/acc a compliance floor, not an option
California’s Proposition 22 moved occupational accident coverage for covered app-based drivers from an optional benefit to a legal requirement. For affected networks, the decision is not simply whether injury protection improves contractor retention or makes financial sense. The operator must manage coverage that meets the law’s requirements.
The California Supreme Court’s July 2024 decision in Castellanos v. State of California upheld the independent-contractor classification provision in state law, section 7451. The court expressly left questions about other provisions open. That distinction limits what the ruling establishes. It should not be described as a blanket judicial endorsement of every part of Proposition 22, even though it upheld the classification provision around which the model is built.
Occ/acc and workers’ compensation also need to remain distinct. Workers’ compensation is designed for employees, while occ/acc provides a means of covering medical costs and lost income from work-related injuries within a contractor network. It is not a workers’ compensation workaround. Nor does the choice of an insurance product, on its own, settle whether a worker has been correctly classified.
Other states can consider California’s model, but it does not show that the same requirements already apply elsewhere. For operators subject to its requirements, however, decentralized voluntary purchasing is a weak foundation for consistent, verifiable protection. Operator-level administration provides a way to maintain coverage across the eligible network. That duty continues after enrollment, so the operator must keep track of whether coverage is still in place.
Why real-time monitoring of coverage status is only practical when the operator holds the policy
Coverage monitoring has to follow the working network. Contractors join and leave, policies change, and deliveries go on between renewal dates. An initial attestation records a point in time. Managing insurance status requires establishing that the required protection remains active when a contractor is dispatched.
Operator-held coverage gives automated credentialing and verification systems a centralized basis for monitoring changes before and during deliveries. The underlying policy relationship sits within the operation’s control rather than behind hundreds of separate purchasing arrangements. That is the practical advantage. With individual policies, current status depends on information from contracts the operator does not administer, and a claim may be the first clear evidence of a lapse.
Retail and 3PL partners make this distinction commercially important because their minimum-limit requirements apply throughout the relationship. Attestations from individual contractors alone cannot show that the whole network continues to meet the requirements. The operator needs a defensible account of current protection. Starting with 2026 payments, the One Big Beautiful Bill Act raises the Form 1099-NEC filing threshold, but that change reduces paperwork rather than tax liability or misclassification exposure.
The infrastructure for coverage monitoring can also support onboarding, credentialing, background checks, and contractor payments. Those functions use the same changing contractor population. Managing them together reduces the synchronization problems that arise when separate tools maintain separate versions of who is active. Insurance control thus becomes part of the operating platform, with value realized both when a policy is purchased and as the network changes.
How operators should structure the transition from individual to bulk purchasing across a live contractor network
Operators should bring coverage together in order of risk and have the system for managing it ready before enrollment begins. Occ/acc is typically the first layer to consolidate because it combines regulatory exposure, visible contractor injury protection, and a clear opportunity for group pricing. For affected app-based networks, this first step also helps meet Proposition 22 requirements as well as save money.
HNOA should follow immediately because it addresses the operator’s exposure from contractor-operated vehicles. This is not protection that can reliably be assembled by asking each contractor to buy insurance for personal needs. Commercial auto for company-owned or leased vehicles and cargo coverage then complete their respective parts of the arrangement, with general liability remaining a distinct layer in the wider stack. The sequence follows the exposure. Its purpose is to close the most consequential contingent-liability gaps first.
Before enrollment starts, operators should have credentialing, coverage monitoring, automated enrollment and offboarding, and payment integration in place. High turnover makes manual administration a poor fit. A live network needs a system that can keep pace with additions and departures, rather than an onboarding project that ends after the first group is enrolled. A unified platform also reduces the data-synchronization failures that occur when insurance administration and contractor status sit in separate tools.
Payment design supports that transition because instant pay and same-day ACH can reduce onboarding friction and help retain contractors. Lower churn, in turn, eases the administrative load of maintaining coverage at scale. Operators with this infrastructure can demonstrate protection to retail and 3PL partners, bring contractors into the network faster, and support compliance without a matching increase in manual work.