Proactive Statutory Standing as the Doctrinal Replacement for Audit-Cycle Compliance in Multi-State Delivery Operations
Continuous compliance monitoring replaces annual audits for multi-state delivery contractors.
For multi-state delivery operators, real-time IC compliance monitoring means keeping classification records, safe harbor enrollment for each jurisdiction, insurance coverage, and payment checks up to date throughout each engagement. Proactive statutory standing shifts the legal and operational work from an annual compliance verdict to checks kept up throughout the year. State portable benefits safe harbors support that posture, but they do not settle federal classification or excuse defects elsewhere in the contractor relationship.
Why the audit cycle is structurally mismatched to the current regulatory environment
As of October 2026, the federal classification standard is not settled. The DOL’s 2024 six-factor rule remains on the books, but its investigators have not applied it since May 2025. A five-factor replacement was proposed in February 2026, and its comment period closed April 28, 2026, without a final rule published by October. Meanwhile, courts in private litigation may apply the 2024 rule or their own circuit precedent. Enforcement policy and litigation exposure do not move together.
This is a design problem. A multi-state operation must meet the IRS common-law rules, the DOL’s economic reality test, and state-specific tests at the same time. A worker can qualify as a contractor under one and an employee under another. The proposed federal replacement would also extend its analysis across the FLSA, FMLA, and MSPA, expanding its statutory reach even as the classification test nominally relaxes. Operators therefore need a posture built for continuing change, rather than an audit schedule premised on eventual regulatory calm.
What the regulatory map actually looks like across active delivery jurisdictions
The IRS common-law test looks at behavioral control, financial control, and the type of relationship. Evidence includes instructions and training, payment methods and expense reimbursement, who supplies tools, and the relationship’s expected continuity. The IRS has no set number of factors that decide the outcome. Its underlying question is whether the hiring entity has the right to control the details of the work.
The DOL asks a different question, namely whether the worker is economically dependent on the hiring entity or genuinely in business for themselves. Under its proposed 2026 framework, control and opportunity for profit or loss would receive dominant weight. Skill, permanence, and integration into a unit of production would be secondary factors. Those are not interchangeable evidentiary requirements.
At least 15 states have stricter tests of their own, while California, Massachusetts, and New Jersey use strict ABC tests that treat workers as employees unless the company proves all three conditions. A multi-state delivery operator consequently manages a compliance portfolio. The same arrangement can produce different legal outcomes depending on where the work occurs and which authority evaluates it.
What proactive statutory standing means and how it differs from audit-cycle compliance
Proactive statutory standing means treating each jurisdiction’s criteria as a live status to satisfy and maintain, rather than a conclusion reached after reviewing a past period. Its limitation belongs in the definition. State portable benefits safe harbors protect compliant benefit contributions from being treated as evidence of employment under state law. They do not provide blanket immunity from reclassification, and they do not change the FLSA economic reality test, IRS common-law factors, or DOL enforcement standards.
Within that boundary, the distinction is substantial. Compliant enrollment and contribution establish a statutory protection before an enforcement event, rather than leaving the operator to assemble a defense after a claim arrives. An audit can discover whether conditions were satisfied, but its conclusion does not activate the protection. The legal benefit comes from meeting the statute’s conditions.
Taking part in a state program affects how benefit contributions are treated, while the working relationship still needs its own classification analysis. Continuous monitoring of both layers is therefore part of the concept.
The enacted state frameworks a delivery operator can act on now
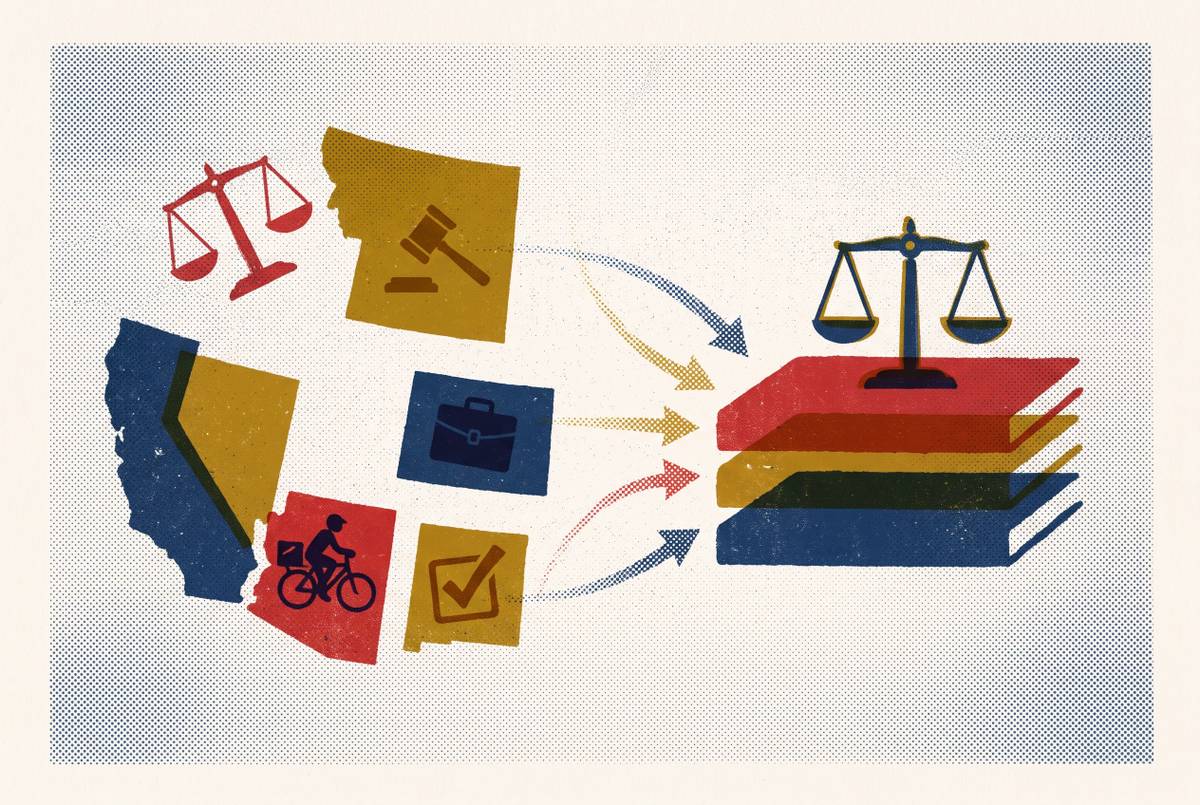
Georgia HB 987 took effect July 1, 2026. It permits voluntary portable benefit contributions for health insurance, paid time off, and retirement without those contributions jeopardizing independent contractor status under Georgia law. Alabama SB 86 adds a financial incentive to its framework. Companies can fully deduct qualifying contributions as a business expense on their Alabama state tax return, and contractors pay no Alabama state income tax on the value received.
West Virginia HB 4009 passed March 14, 2026. It permits contributions to a worker’s portable benefit account without using those contributions to establish an employment relationship. Kansas HB 2602, enacted in March 2026, also allows contributions for gig workers without treating them as evidence of employment. Tennessee and Utah have also enacted portable benefits laws, with benefit types and contribution structures that differ by state.
Program design therefore must follow each state’s statute. Nine additional states introduced similar bills in the first month of the 2026 legislative session, but introduced legislation creates no actionable standing. The federal Unlocking Benefits for Independent Workers Act, S.2210, is also advancing toward enactment.
Why misclassification risk in last-mile delivery is disproportionate, not merely generic
Last-mile delivery concentrates a disproportionate share of logistics costs in the part of the network where contractor classification is most consequential. The workforce is both a major operating cost variable and a concentrated source of liability. An adverse finding is rarely confined to one driver. When workers perform similar work under the same arrangement, a reclassification determination can extend across the contractor roster.
Employment taxes are one part of the risk that follows. IRC section 3509 provides reduced rates in certain misclassification circumstances, but intentional disregard of withholding requirements removes access to those rates. Intent is not required for liability itself. Separately, Section 530 can provide relief where an employer has a documented reasonable basis and meets its requirements.
Documentation is therefore an operating control. High contractor volumes and continuing onboarding mean exposure accumulates with every undocumented engagement. When one arrangement can replicate risk throughout a network, an annual review leaves too much time between creating the exposure and discovering it.
How do delivery operators monitor IC compliance continuously instead of running quarterly audits?
Credential expiration does not respect the audit calendar. A driver license can expire mid-year, commercial auto coverage can lapse, and an occupational accident certificate may never have been verified at onboarding. Each gap opens when the underlying condition changes. Monitoring must follow those events as they occur.
Legislation has its own schedule as well. A January 2026 audit would not record Georgia’s subsequently effective safe harbor as an available protection. A contractor compliantly enrolled on July 2 could therefore have a different benefits-related legal posture from the same contractor on June 30. Federal rulemaking creates a parallel need to distinguish the standard used in the last review from the one relevant to current enforcement or litigation.
Operators need classification review before each engagement and whenever the work changes, coupled with continuing credential, coverage, and legislative monitoring. That cadence follows the sources of exposure directly. Across a delivery network, that cadence must be part of how contractors are managed rather than an extra inspection bought from time to time.
What proactive standing requires at the onboarding and credentialing stage
The posture begins before the first engagement. Classification documentation, credential verification, and insurance confirmation need to be current then, rather than reconstructed from incomplete records during an inquiry. License verification, background checks, vehicle documents, insurance confirmation, and jurisdiction-specific regulatory training each have their own timelines. Treating them as one completed onboarding box obscures those differences.
Serial processing makes the gap harder to control. Paper forms re-keyed into systems and checks triggered one after another accumulate delays at each handoff. With continuous onboarding and offboarding, that approach makes it difficult to demonstrate that every active contractor’s documentation is current. Running checks in parallel and letting staff see which requirements are still unmet helps clear the documentation bottleneck as well as ease the paperwork.
One last-mile delivery company automated onboarding workflows through email-triggered next steps and a centralized dashboard for document collection and background checks. It recovered meaningful administrative time within weeks. The example shows that the operational shift is achievable, without making automation a substitute for sound classification. The IRS recommends documenting each factor relied on at classification, while collecting a W-9 and validating the TIN before payment establishes the tax record at the same starting point.
The insurance stack that gives proactive standing operational completeness
Enrolling in portable benefits leaves insurance exclusions in place. Most personal auto policies exclude commercial delivery use, so a contractor who relies on one has no coverage for that delivery risk. Waiting for an order can create another gap. With the app on, most personal policies do not cover that phase, while platform-provided policies often offer limited or no protection.
Contractors classified as independent contractors do not qualify for employer workers’ compensation, while occ/acc provides medical and disability income protection for delivery injuries. It does not replace commercial auto coverage. Cargo coverage, where needed, covers the risk to the goods, which is separate from the driver’s injury or vehicle liability.
Occ/acc can be rated per mile, delivery, task, hour, or other periods and measures, allowing coverage costs to track fluctuating engagement volume. Buying commercial auto and occupational accident coverage in bulk can lower the cost for each contractor and close gaps left by policies bought one at a time.
How payment infrastructure closes the compliance loop and why pay speed is not separable from compliance posture
The payout flow connects onboarding records to continuing tax compliance. Collecting W-9s and W-8s at registration supports automated 1099-NEC and 1042-S generation at filing time, while TIN validation and sanctions screening place checks within the payment process. Payment systems help keep classification documentation in order, though paying someone through a contractor system does not make that person a contractor.
Some states require separate filings and others do not, so retrospective assembly creates opportunities for missing income, discrepancies, and costly corrections after deadlines. Centralized payment data provides the basis for managing those distinct obligations. One federal filing workflow cannot stand in for every state requirement.
Pay speed also affects the volume of compliance work. Slow pay leads contractors to leave, so their replacements need fresh classification and credential checks and new enrollment for benefits they are eligible for. RTP and FedNow settle around the clock throughout the year, while Same-Day ACH operates within business-day windows. For a workforce active on weekends and holidays, that difference affects timely payment, retention, and the cost of maintaining current records, as well as applicable state wage-payment timing obligations.
Building the proactive standing posture across all four operational layers
The operating model has four simultaneous layers. Classification documentation comes first, with contemporaneous, factor-by-factor records under applicable federal and state tests before engagement, updated when the work changes. A documented reasonable basis supports the operator’s legal position, but Section 530 relief should not be confused with section 3509’s reduced tax rates. Neither provision turns incomplete documentation into automatic protection.
Jurisdictional enrollment is the second layer, and insurance completion is the third. Enrollment records must reflect where a contractor works and which enacted framework applies, because protection in one state does not establish it elsewhere. Operators must confirm insurance for commercial auto, occupational accident, and applicable cargo exposures, then keep checking that coverage is current after onboarding. An expired certificate signals a coverage question.
Payment-embedded compliance completes the model through tax-form collection, TIN validation, reporting, state-specific filing management, and timely settlement.
At delivery-network scale, maintaining these functions as separate manual processes leaves staff tracking concurrent engagements, expirations, enrollments, and payment cycles without a common operating view. A purpose-built contractor workforce management platform unifying onboarding, real-time compliance monitoring, insurance administration, and payments makes the posture maintainable. The selection criterion is that combined capability. Audits can still examine the system, but they can no longer serve as the system itself.